What is IT consultant insurance?
IT consultant insurance isn’t a single insurance product; it’s several products that, when combined, meet the specific needs of your particular IT consulting business.
Because IT consultants give advice, professional indemnity is an essential cover to have in place. Public liability may also be required if you do a lot of face-to-face work. Consultants can add portable electronics insurance if they rely on expensive computer equipment.
Why do IT consultants need insurance?
As an IT consultant, at some point, you will come across a client who will contractually require you to have certain types of insurance, such as professional indemnity.
However, contractual obligations aside, it's worth asking, “What other risks do I face?” “Should I be operating without the right insurance?” and “How will it protect me?”
Working independently sometimes doesn’t go according to plan. As a self-employed IT consultant, you will be the one to ultimately face any challenges that come with running your own business.
Contract compliance
Most contracts you will engage with as an IT consultant will stipulate you must have and show proof of certain types of insurance, but this should never be just a box-ticking exercise.
Accusation of causing a financial loss
An unhappy client may allege your work or advice ended up costing them money, which they now want to recover from you.
Property damage or injuries caused by you
If you work on a client site or spend much time meeting customers face-to-face, you may also risk damaging someone else's property or causing personal injury.
Damage to your work equipment
You are likely to use a laptop or computer for your work, and if that gets stolen or damaged, the repair or replacement costs could be expensive.
Professional indemnity insurance for IT consultants
Professional indemnity insurance is the first insurance policy IT consultants should consider due to the advisory nature of their work.
You may be consulting in several areas, such as cyber security, system integration, application migration or architecture, with much of your work being strategic, involving recommendations and a high level of responsibility.
Working as a consultant comes with inherent risks, so professional indemnity insurance is critical whether or not your contract requires it.
Professional indemnity is a legal cover that insures IT consultants against professional mistakes, accusations of negligence, breach of confidentiality and more. It covers the associated cost of a legal defence and will pay any compensation if you are found liable.
What does IT consultant professional indemnity insurance cover?
Professional indemnity protects IT consultants from legal claims or accusations of wrongdoing stemming from their professional advice or work product.
Cover includes:
- Giving the wrong advice or recommendation
- Making a mistake
- Acting negligently
- Failing your duty of care
For example:
- An unclear brief has led to unmet client expectations. The client may demand a remedy at your cost.
- Your recommendation or advice led to your client’s system failure, costing them money. They are asking you to pay for the loss.
- Demands of compensation due to delays, errors, or incomplete work causing financial losses
- The leak of sensitive or confidential information
As an IT consultant, the risk of facing one of the above or another issue resulting from providing advice in the technology space has increased directly in line with the uptake of technology in pretty much every industry.
What professional indemnity does not cover
Professional indemnity does not typically cover claims arising from loss of data or cyber risks. Cyber incidents are matters such as:
- software or a computer system failing or becoming unavailable
- loss, corruption or unauthorised disclosure of electronic data
- hacking or unauthorised access to a computer system
- a security weakness or vulnerability in software
- the transmission of a virus or malicious software
How much professional indemnity does an IT consultant need?
Professional indemnity insurance comes with a choice of cover limits. A few things can help put those figures into context.
Your clients may have minimum insurance requirements, either in their contracts or as part of their procurement process. Asking whether they have any specific requirements can be a useful starting point.
Another consideration is what could happen if something went wrong. If a client blamed your work for a serious problem, how much could they claim? The size of the project, the client’s business and how much they rely on your work can all affect the potential consequences.
Legal costs can also add to the expense of a claim. Whether these sit within your cover limit or are paid in addition depends on the policy.
Cancelling your professional indemnity insurance
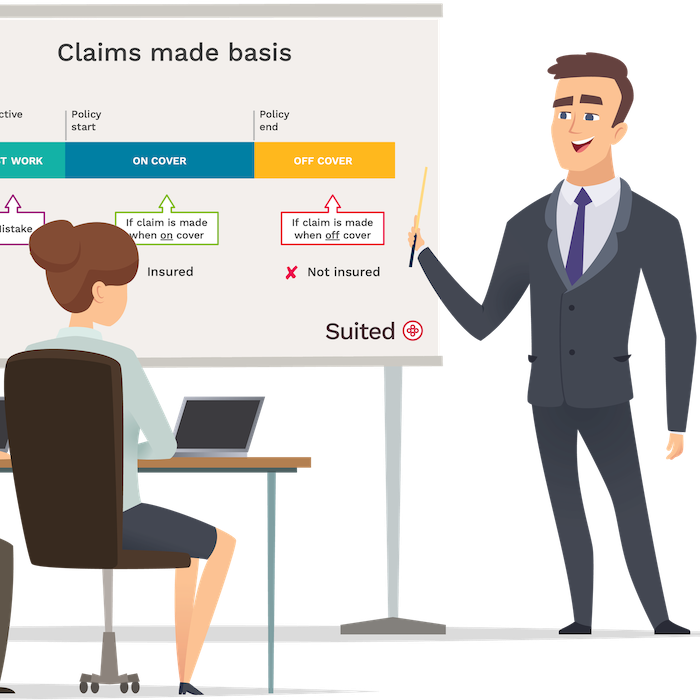
If you decide to cancel your professional indemnity insurance, bear in mind that claims can arise long after you’ve finished the work. Once your policy is cancelled or expires, it generally won’t cover new claims against you, even if the work was done while you were insured.
Finished working or taking a break? Ask us about Suited’s hibernation option.
Should I retain professional indemnity insurance if I am between contracts?
It’s wise to keep your professional indemnity if you’re taking a break or retiring from IT consulting. Claims against professional misconduct can surface months or years after you delivered the work.
Remember: If you cancel your policy, your insurance coverage will end, including coverage for any previous work.
How long you keep your cover in place is up to you. Consider the type of IT consulting you did and the likelihood that a client might bring a claim against you.
Public liability insurance for IT consultants
If you regularly consult with clients face to face or work at their premises, public liability insurance is wise. Public liability protects you against accusations of causing an accident leading to an injury or property damage.
Public liability can be inexpensive protection against unfortunate incidents such as slips, falls, or you causing damage to a third party’s property. Public liability claims rarely result in substantial compensation, but legal defence costs can add up.
What does IT consultant public liability insurance cover?
Public liability is helpful when faced with injury claims and compensation demands.
Cover includes:
- accidental injury or death
- accidental property damage
For example:
- A client visits your premises and is injured in a slip or fall
- You visit your client’s premises and accidentally damage expensive IT equipment
Other insurance IT consultants buy
As an IT consultant, the additional insurance coverage you require will depend on your situation. It is important to consider if you have the financial capability to replace or repair any computer equipment that gets damaged. Additionally, it is wise to consider how you would handle a legal dispute, as well as what steps to take in case of a tax audit by HM Revenue & Customs.
Portable electronics insurance
As an IT consultant, you’ll likely rely on everything electronic to deliver your work. As such, you may consider adding portable electronics insurance to cover your computer kit.
Portable electronics insurance will cover the cost of repair or replacement if your equipment is lost, damaged or stolen.
Cyber insurance
IT expertise doesn’t make your own business immune to a cyber attack. Compromised systems or stolen data can disrupt your work and leave you with unexpected costs. Cyber insurance can help with the costs of responding to an attack and getting your business back up and running.
Cyber cover isn’t available through Suited’s online quote process, but we can help arrange it. Get in touch to discuss your business.
Office insurance
If your IT consultancy operates from an office, there’s more to consider than the laptops on your desks. Computers, monitors, furniture and other equipment can soon add up. Office contents insurance can help with the cost of replacing these items following events such as fire or theft.
We can also help arrange office cover. Contact us to discuss your requirements and get a quote.
IT consultants we insure
Suited provides insurance coverage for a diverse group of IT consultants, including:
- Computer consultants
- CRM systems consultants
- Cyber security consultants
- Database consultants
- Disaster recovery consultants
- Software consultants
- Technology consultants
- Telecommunication consultants
- Website/Mobile app consultants
- and more...
Common questions
Do I need retroactive cover with my IT consultant professional indemnity insurance?
You may need retroactive cover if there is a possibility that the work you did in the past may result in a claim in the future. You may also need it if your past contract requires to stay insured for a period of time after you finished the contract. If you're switching from one insurance provider to another, you will have to specify a retroactive date on your new policy if you want your past work insured. This is because the new insurance provider is effectively taking over the risk of a claim from the previous insurance provider.
What is not covered by IT consultant professional indemnity insurance?
You need to remember that PI cover protects from claims of professional negligence or error. Therefore any other issues such as your liability to your employees if you have any, the public or third party property won’t be covered. The same applies to cyber risks.
Can I make a claim after I have cancelled my IT consultant professional indemnity insurance?
You won't be able to make a claim under a policy that is no longer active. If you have finished a contract or wound down your IT consultancy business, make sure you maintain professional indemnity cover for your past work for a period of time. This is often referred to as a run off cover.
What is a ‘run off’ cover in IT consultancy insurance?
When a contract ends, the liability for the work you have delivered still exists and you may be either contractually required or wish to keep professional indemnity insurance in place for a little while longer. In Suited we call this option ‘hibernation’ which means you can change your PI cover to stay insured the past only at a much reduced price if you are not planning to take on another contract.
CEO of Suited, with 20 years’ experience in business insurance, focused on building flexible, digital insurance solutions for SMEs and self-employed professionals.
Co-founder of Suited and insurance technology specialist, highly experienced in designing and delivering digital insurance solutions for SMEs and the self-employed.
Note
This guide is for informational purposes only and does not constitute advice or a personal recommendation.