What is IT contractor insurance?
IT contractor insurance isn’t a single product; it’s a combination of products that meet your particular needs as an IT contractor.
IT contractors adopt many roles, but for any job, your contract will likely require you to have professional indemnity insurance. Public liability can also be a contractual obligation, and if you rely on your computer gear for your income, portable electronics insurance comes in handy.
Why do IT contractors need insurance?
Contract compliance
As an IT contractor, most engagements you enter into will stipulate in the contract that you must have and show proof of professional indemnity insurance.
However, being self-employed, you are ultimately responsible for any wrongdoing caused by your actions, so you should consider professional indemnity insurance more than just a box-ticking exercise.
Accusation of causing a financial loss
An unhappy client may allege your work product was substandard or resulted in a financial loss that they now want to recover from you.
Damage to your work equipment
You are likely to use your laptop or computer for your work. Could you afford the repair or replacement costs if that gets stolen or damaged?
IT contractor professional indemnity insurance
Professional indemnity insurance can help with legal costs and compensation if a client claims that a mistake in your work has cost them money.
You might recommend unsuitable software, overlook a key requirement in a specification or give incorrect technical advice. If your client has to pay to put things right, they could seek to recover those costs from you.
Some companies require IT contractors to have professional indemnity insurance before work begins. Even if you believe you’ve done nothing wrong, defending a claim can be expensive.
What does professional indemnity insurance for IT contractors cover?
Professional indemnity protects you from claims or accusations of wrongdoing from your professional IT advice or work product.
Cover includes:
- Failing your duty of care
- Making a mistake
- Acting negligently
- Giving the wrong advice or recommendation
For example:
- You recommend software that’s incompatible with your client’s existing setup, leaving them with additional costs to replace it.
- You overlook a key technical requirement when preparing a specification, causing your client to incur extra development costs.
- You make a mistake configuring a retailer’s pricing software, causing products to be sold below their intended prices.
- You build a reporting tool that calculates stock requirements incorrectly, leading your client to purchase goods they don’t need.
What professional indemnity does not cover
Professional indemnity insurance typically excludes liability you accept under a contract that goes beyond what you would otherwise be legally responsible for, such as agreed penalties or guarantees of results.
Cyber risks, including cyber attacks, data breaches and loss of data, may also be excluded and require separate specialist cover.
What professional indemnity limit do IT contractors need?
Your work contract often dictates the minimum professional indemnity limit required.
If you have yet to receive your contract, ask your client or recruitment agency for the details so that you have enough time to explore your insurance options.
Check if the professional indemnity limit needs to be "any one loss" and how long you'll need to keep the cover in place after finishing the contract.
Some IT contracts specify a minimum professional indemnity insurance limit. Higher limits generally mean higher insurance costs. These requirements are sometimes negotiable, depending on the client and the contract.
Where no minimum is specified, relevant factors include your role in the project, the extent of your responsibility and the potential financial consequences if something goes wrong.
A contract may also contain a limitation of liability clause. This sets out the agreed limits of your liability to the client, which is different from the amount of insurance the contract requires you to hold.
Any one loss vs. in the aggregate
IT contracts rarely stipulate whether the professional indemnity limit can or cannot be “in the aggregate”.
“In the aggregate” limit is a cover restriction, which means that irrespective of the number of claims you make during the period of insurance, you are only covered up to the policy limit across all claims.
For example, if you've bought a £1,000,000 PI policy and your first claim was £800,000, you only have £200,000 of PI cover remaining until your insurance renewal. Some IT contracts may require that your PI insurance is on an "any one loss" basis, which means your policy covers you up to the full policy limit per every claim.
Number of years
Some IT contracts require you to stay insured for up to 6 years after your contract finishes; you may be able to negotiate this for a shorter period.
Cancelling your professional indemnity insurance
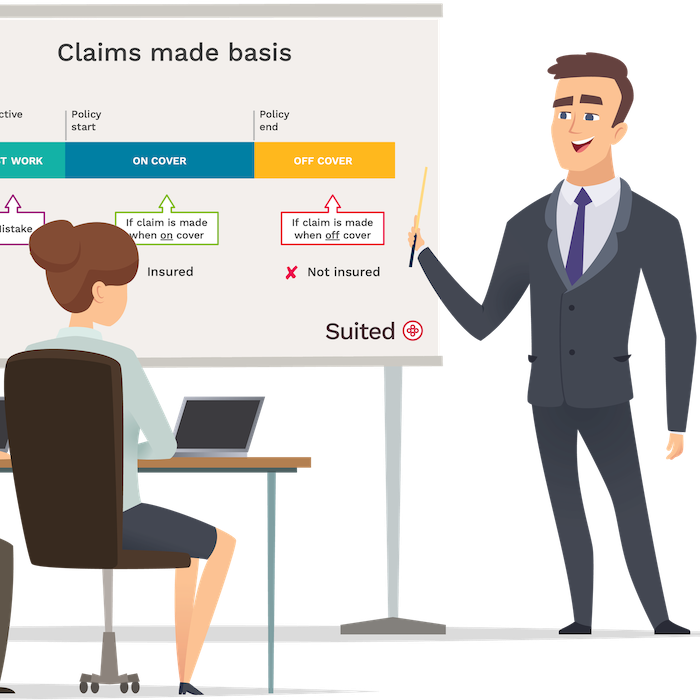
If you decide to cancel your professional indemnity insurance, bear in mind that claims can arise long after you’ve finished the work. Once your policy is cancelled or expires, it generally won’t cover new claims against you, even if the work was done while you were insured.
Finished working or taking a break? Ask us about Suited’s hibernation option.
Should I retain professional indemnity if I am between contracts?
It’s wise to keep your professional indemnity if you’re taking a break or retiring from IT contracting. Claims against professional misconduct can surface months or years after you delivered the work.
Remember: If you cancel your policy, your insurance coverage will end, including coverage for any previous work.
How long you keep your cover in place is up to you. Consider the type of IT contracting you did and the likelihood that a client might bring a claim against you.
IT contractor public liability insurance
In some cases, your contract may also require you to have public liability insurance.
Public liability protects you against accusations of causing an accident leading to an injury or property damage.
Public liability can be inexpensive protection against unfortunate incidents such as slips, falls, or you causing damage to a third party’s property.
What does IT contractor public liability insurance cover?
Public liability is helpful when faced with injury claims and compensation demands.
Cover includes:
- accidental injury or death
- accidental property damage
For example:
- A client visits your premises and is injured in a slip or fall
- You visit a client site and damage equipment by knocking over a coffee
Other insurance IT contractors buy
If you work as an IT contractor, the kind of insurance coverage you need will vary based on your circumstances. Do you have the necessary financial means to replace or repair damaged computer equipment? Could you handle a legal dispute? What would you do if you had a tax audit by HM Revenue & Customs?
Portable electronics insurance
As an IT contractor, you likely depend heavily on electronic devices to complete your work. In the event that these devices are lost, damaged, or stolen, the cost of replacing them and maintaining your workflow could be significant.
To address this risk, it is wise to consider obtaining portable electronics insurance. Doing so can help you mitigate potential losses and get back to work as quickly as possible.
Cyber insurance
As an IT contractor, you may rely on your own systems to access client information, manage projects and deliver your work. A cyber attack or data breach affecting your business can leave you facing disruption and unexpected costs. Cyber insurance can help with specialist support and the costs of responding to an incident.
Suited can help arrange cyber insurance, although it isn’t available through our online quote process. Get in touch to discuss cover for your IT contracting activities.
IT contractors we insure
Suited provides insurance coverage for a broad spectrum of IT contractors, including:
- IT project managers
- IT business analysts
- Computer programmers
- Systems analysts
- Database administrators
- Data architects
- Data recovery specialists
- IT infrastructure service providers
- IT network and systems engineers
- IT penetration testers
- and more...
Shopping for IT contractor indemnity insurance
When shopping for IT contractor insurance to safeguard your business, it's important to consider the following:
Cheap IT contractor insurance
When searching for IT contractor insurance, it's important to consider more than just the cost. The quality of after-sales service is crucial. Make sure to check how easy it is to reach your insurance provider. At Suited, we offer multiple contact options and respond promptly to ensure your peace of mind.
The reputation of the insurer is important
Insurance is critical during times of need, so it's crucial to assess the payout reputation of your insurer. At Suited, we’re selective about the insurers we work with.
Many providers charge fees to amend or cancel
A low headline price can come with extra charges for paying monthly, changing your policy or cancelling. At Suited, we don’t charge these fees. You can cancel your monthly subscription at any time, and future payments stop immediately.
Some policy wordings are restrictive or have a high excess
Some providers will offer attractive prices, but it is at the expense of cover given. Suited professional indemnity and public liability have £0 excess.
Common questions
Can I get my past work covered by Suited IT contractor insurance?
Yes, Suited offers a retroactive cover option. When buying your PI insurance, select the date from which you'd like to be covered and it will show on your policy schedule as the "retroactive date".
Will the work of my subcontractors be covered by Suited IT contractor professional indemnity insurance?
Yes, any work by subcontractors of your business is covered, however, do not waive your rights to hold them liable and you should insist that they have PI insurance.
Do IT contractors need public liability insurance?
That depends whether you come into a regular face to face contact with your clients, handle their property (computer hardware, etc) or deliver your services outside your usual place of work, for example at your client's premises. If any of the above applies to your business then you may wish to consider public liability insurance to additionally protect your business against any mishaps such as causing an injury or property damage.
How is the cost of IT contractor professional indemnity insurance calculated?
At Suited we only take into account your annual turnover, that's it. We do not charge per person.
CEO of Suited, with 20 years’ experience in business insurance, focused on building flexible, digital insurance solutions for SMEs and self-employed professionals.
Co-founder of Suited and insurance technology specialist, highly experienced in designing and delivering digital insurance solutions for SMEs and the self-employed.
Note
This guide is for informational purposes only and does not constitute advice or a personal recommendation.